ACCA IAS 10 Events After the Reporting Period ACCA Notes by PW
 Mehjabeen Hussain31 Oct, 2026

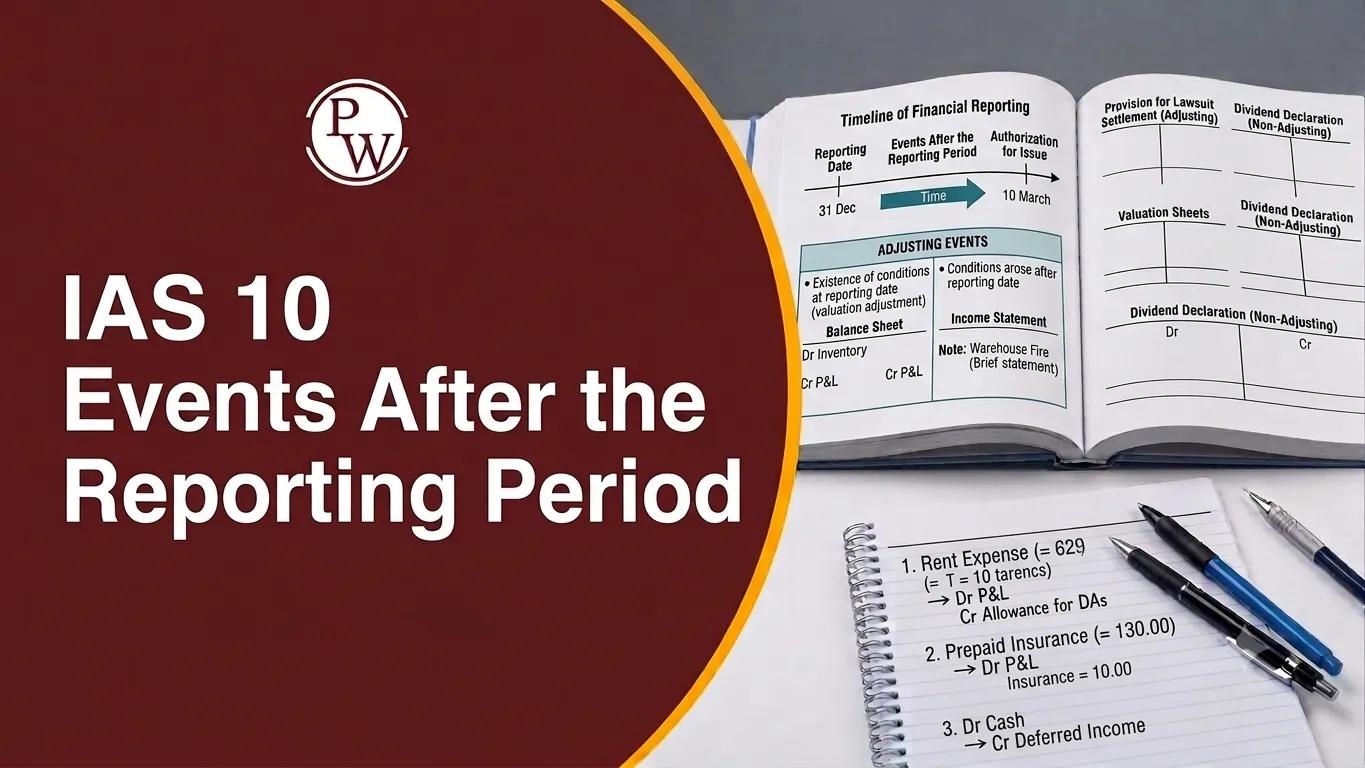
IAS 10 Events After the Reporting Period explains how events occurring between the reporting date and the date when financial statements are authorised for issue are considered in financial reporting. Understanding the distinction between adjusting and non-adjusting events is important for determining whether financial statements need to be adjusted or whether an event should be disclosed.
To strengthen your ACCA Financial Accounting preparation, the IAS 10 Events After the Reporting Period ACCA PDF by PW covers the key areas of the standard, including the IAS 10 timeline, accounting treatment, disclosures, going concern principles and dividends declared after year-end. Revising these concepts can help you understand how events after the reporting period are reflected in financial statements.
What is IAS 10 Events After the Reporting Period?
IAS 10 deals with events that occur after the reporting period and before the financial statements are authorised for issue. The standard helps determine whether these events require an adjustment to the financial statements or disclosure in the financial statements.
IAS 10 Timeline
The IAS 10 timeline covers the period from the end of the reporting period to the date when the financial statements are authorised for issue. Identifying this period is important when determining how an event occurring after year-end should be treated.
Adjusting and Non-Adjusting Events
Events after the reporting period are broadly classified as adjusting events and non-adjusting events. Adjusting events provide evidence of conditions that existed at the end of the reporting period and require the financial statements to be adjusted.
Non-adjusting events indicate conditions that arose after the reporting period. These events do not result in adjustments to the recognised amounts, although material events may need to be disclosed.
Going Concern and IAS 10
Going concern is another important area considered under IAS 10. If events occurring after the reporting period indicate that the going concern assumption is no longer appropriate, the financial statements may need to be prepared on a different basis.
Dividends Declared After Year-End
Dividends declared after the reporting period are also considered under IAS 10. Where dividends are declared after the reporting period, they are not recognised as a liability at the end of that reporting period. Relevant disclosure requirements may apply.
IAS 10 and IAS 37
IAS 10 and IAS 37 can be relevant when events occurring after the reporting period affect the recognition or measurement of liabilities and provisions. Understanding the relationship between the two standards helps in applying the appropriate accounting treatment to relevant events.
IAS 10 Events After the Reporting Period ACCA PDF
The IAS 10 Events After the Reporting Period ACCA PDF covers the key concepts required to understand the accounting treatment of events after the reporting period. It includes the IAS 10 timeline, adjusting and non-adjusting events, disclosure requirements, going concern principles and dividends declared after year-end.
IAS 10 Events After the Reporting Period ACCA PDF
Why Choose IAS 10 Events After the Reporting Period ACCA PDF by PW?
IAS 10 involves identifying events that occur after the reporting period and determining whether they require adjustment or disclosure. Revising the IAS 10 ACCA PDF alongside related PW resources can help you understand these accounting treatments and apply the standard more confidently in Financial Accounting questions.
Understand Events After the Reporting Period with Revenue Recognition and Events After the Reporting Period
Revise the key concepts of IAS 10, including adjusting and non-adjusting events, with the detailed explanation of events after the reporting period.
Build Your Financial Accounting Foundation with ACCA Financial Accounting (FA) Complete Guide
Connect IAS 10 concepts with other Financial Accounting topics and revise the fundamentals covered in the ACCA FA paper.
Revise the Relevant Topics with ACCA FA Syllabus 2026
Use the syllabus to understand where Events After the Reporting Period fits within the ACCA Financial Accounting topics and organise your revision accordingly.
Organise Your Revision with Published Financial Statements
Relate IAS 10 adjustments and disclosures to the preparation and presentation of published financial statements.
Connect IAS 10 with IAS 37 Provisions, Contingent Liabilities and Contingent Assets
Revise IAS 10 alongside IAS 37 to understand how events after the reporting period can relate to provisions, contingent liabilities and other accounting treatments.
The IAS 10 Events After the Reporting Period ACCA PDF brings together the key areas needed to revise IAS 10, including the reporting-period timeline, adjusting and non-adjusting events, accounting treatment and disclosure requirements. It can be used for focused revision while preparing for ACCA Financial Accounting.
FAQs
What is IAS 10?
Why is the IAS 10 timeline important?
What are the key areas to understand in IAS 10?
What topics are covered in the IAS 10 Events After the Reporting Period ACCA PDF?


Have questions about your prep?
Our experts can answer all your questions