ACCA Trial Balance and Incomplete Records Notes by PW
 Mehjabeen Hussain31 Oct, 2026

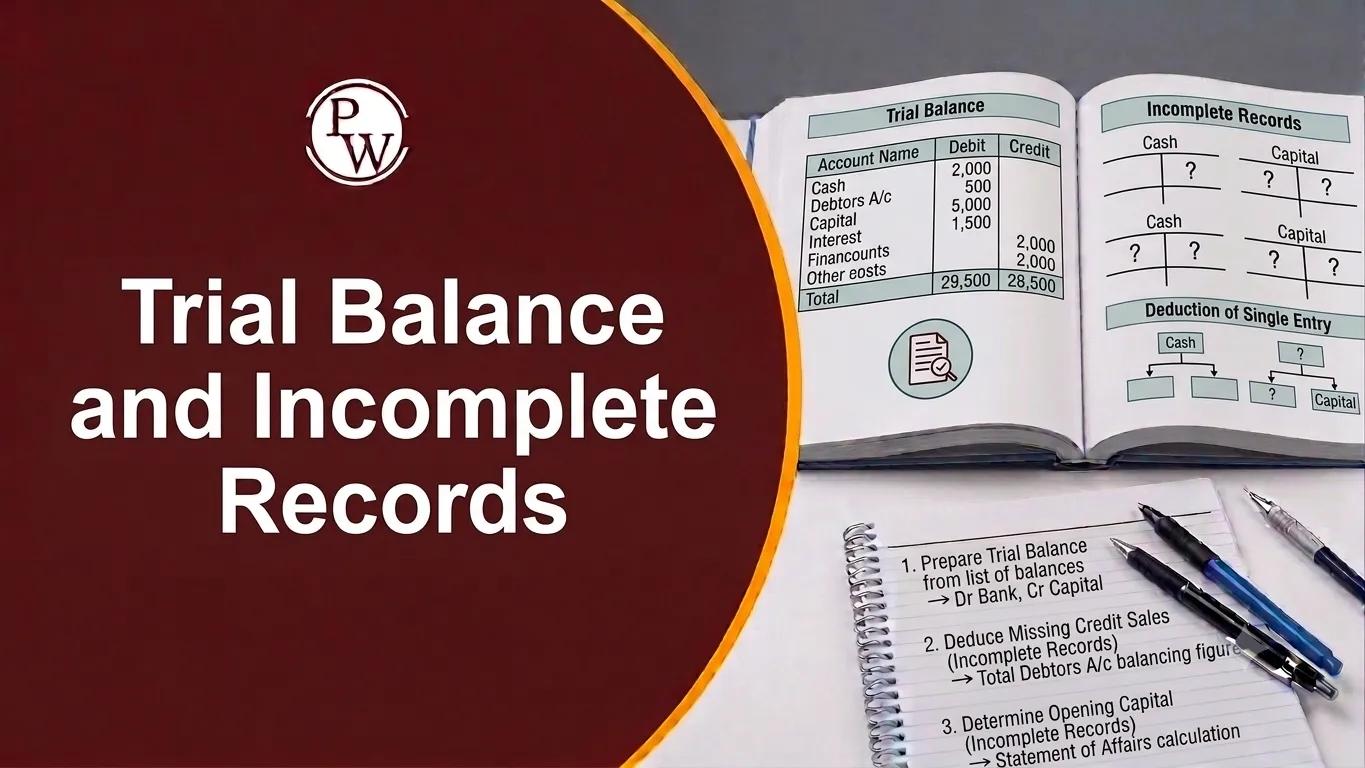
A trial balance brings together the closing debit and credit balances from the general ledger and provides a starting point for preparing financial statements. However, an agreement between total debits and credits does not guarantee that the accounting records are completely free from errors.
PW provides the Trial Balance and Incomplete Records ACCA notes that cover the preparation and correction of a trial balance as well as the treatment of incomplete accounting records. The PDF explains how missing figures can be derived from ledger accounts and how the accounting equation, mark-up and margin can be used when complete records are not available.
Trial Balance
A trial balance is a list of the closing debit and credit balances from the individual accounts in the general ledger. Asset and expense accounts generally have debit balances, while liability and income accounts generally have credit balances.
The trial balance is used to check whether transactions have been posted according to the principles of double-entry bookkeeping. It also provides a starting point for preparing financial statements.
However, a trial balance cannot identify every type of error in the accounting records. Some errors may still exist even when total debit and credit balances agree.
Preparing a Trial Balance
Preparing a trial balance involves closing the individual ledger accounts and identifying their balances. These balances are then brought together to form the initial trial balance.
Errors identified during the process are corrected using appropriate accounting entries. Year-end adjustments, such as irrecoverable debts, accruals and provisions, are then recorded before preparing the final trial balance.
Errors in the Trial Balance
Errors in accounting records can cause the trial balance not to agree. Investigating the difference helps identify the underlying accounting error and determine the required correction.
A trial balance may also agree even when errors are present. Therefore, agreement between total debits and credits should not be treated as proof that every accounting entry has been recorded correctly.
Suspense Account and Error Correction
A suspense account can be used temporarily when the trial balance does not balance and the cause of the difference has not yet been identified. Once the error is found, the appropriate correction is made and the suspense account is cleared.
Understanding error correction and suspense accounts is important when moving from the initial trial balance to the final trial balance.
Incomplete Records
Incomplete records arise when a business does not maintain a complete set of accounting records. In such cases, missing figures may need to be calculated using the information that is available.
The accounting equation can be used to derive missing amounts, while ledger accounts can also help determine figures such as missing sales, purchases or balances.
Mark-up and Margin
Mark-up and margin are useful when working with incomplete records and determining missing figures relating to sales, cost of sales and gross profit. Understanding the difference between mark-up and margin is important when applying these calculations to accounting information.
Trial Balance and Incomplete Records ACCA PDF
The Trial Balance and Incomplete Records ACCA PDF covers the key areas needed for revision, including the nature and preparation of a trial balance, errors and their correction, suspense accounts, year-end adjustments and incomplete records. It also covers the use of the accounting equation, ledger accounts, mark-up and margin to derive missing figures.
Trial Balance and Incomplete Records ACCA PDF
Why Choose Trial Balance and Incomplete Records ACCA PDF by PW?
Trial Balance and Incomplete Records involves checking ledger balances, identifying and correcting errors, using suspense accounts and deriving missing figures when accounting records are incomplete. Revising these areas through the ACCA PDF can help you understand how bookkeeping information is checked, corrected and used in preparing financial statements.
Strengthen Trial Balance Concepts with Adjustments to Profit and Suspense Accounts
Revise trial balance differences, error correction and suspense account treatment with this related PW resource.
Revise Trial Balance Preparation with ACCA Financial Accounting (FA) Complete Guide
Strengthen your understanding of double-entry bookkeeping, ledger accounts, trial balances and their role in preparing financial statements.
Place Incomplete Records Within the ACCA FA Syllabus 2026
Use the syllabus to connect incomplete records, correction of errors and trial balance preparation with the relevant areas of ACCA Financial Accounting.
Strengthen Your Overall FA Revision with ACCA Financial Accounting (FA/F3)
Explore the wider Financial Accounting concepts related to bookkeeping, financial statements and accounting records while revising the topics covered in the chapter.
Continue Revising Financial Accounting with ACCA FA Examiner’s Report
Review the examiner’s guidance alongside trial balance and incomplete records to understand common areas of difficulty and improve your approach to ACCA Financial Accounting questions.
The Trial Balance and Incomplete Records ACCA PDF brings together the accounting steps involved in preparing a trial balance, identifying and correcting errors, using suspense accounts and dealing with incomplete records. It can support focused revision of these areas while preparing for ACCA Financial Accounting.
FAQs
What is a trial balance?
What is the purpose of a trial balance?
Can a trial balance agree even when there are errors?
What are incomplete records?


Have questions about your prep?
Our experts can answer all your questions